💰 Show-Money Calculator for Student Visas
How much money Indian students must show for a student visa in Canada, the UK, Australia, the USA, Germany, New Zealand and Ireland, in rupees, how long to hold it, accepted documents, and an education loan EMI and TCS calculator.
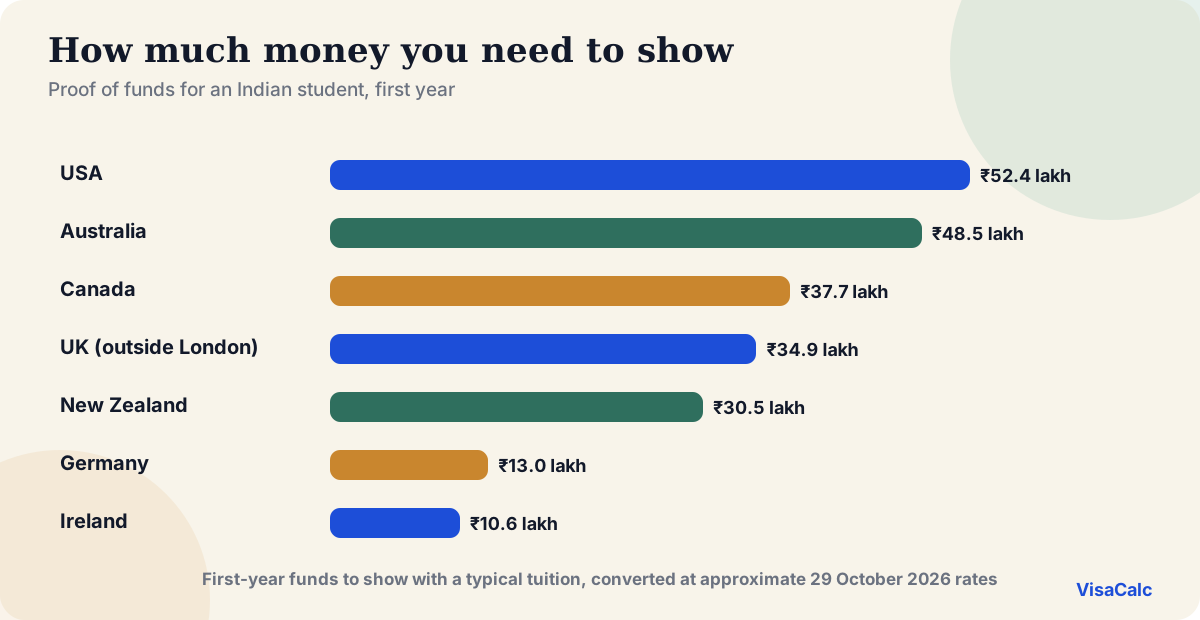
Worked example: first-year funds with a typical tuition
| Country | Show at least | In rupees (approx., 29 Oct 2026) |
|---|---|---|
| 🇨🇦 Canada (outside Quebec) | C$55,448 | ₹37,69,420 |
| 🇬🇧 UK (outside London) | £27,539 | ₹34,92,158 |
| 🇦🇺 Australia | A$72,210 | ₹48,46,686 |
| 🇺🇸 USA | $55,000 | ₹52,41,280 |
| 🇩🇪 Germany | €12,204 | ₹12,96,247 |
| 🇮🇪 Ireland | €10,000 | ₹10,62,149 |
| 🇳🇿 New Zealand | NZ$57,000 | ₹30,54,874 |
Tuition varies a lot by university and course: use your own offer letter in the calculator. US figures use the first-year total printed on a typical I-20.
Worked example: a ₹30 lakh education loan
| Interest added to the loan | Interest paid during the course | |
|---|---|---|
| Interest during 2-year course + 6-month grace (10.5%) | ₹7,87,500 | ₹7,87,500 (paid monthly) |
| EMI for 10 years after that | ₹51,107 | ₹40,480 |
| Total interest | ₹31,32,796 | ₹26,45,160 |
Paying the interest while you study (often possible from part-time earnings or family) cuts the EMI and the total cost. Many Indian banks charge simple interest during the moratorium, as assumed here; check your sanction letter.
Mistakes that get funds rejected
- Large deposits just before applying without a sale deed, loan letter or gift deed explaining them.
- Funds in a relative's name the country does not accept (the UK accepts only you or your parents).
- Breaking the UK 28-day rule by dipping below the amount for even one day.
- Showing property or gold instead of money. Use them to explain the source, not as the funds.
- Fake or "arranged" bank statements from agents. This is treated as fraud and can bring a ban of years.
Frequently Asked Questions
How much bank balance is needed for a Canada student visa from India?
From 1 September 2026, at least C$23,448 for living costs (C$24,617 in Quebec) plus your first-year tuition and return travel. With C$30,000 tuition and C$2,000 travel that is C$55,448, about ₹37,69,420 at 29 October 2026 rates.
What is the 28-day rule for a UK student visa?
The money must sit in the account for 28 consecutive days without dropping below the required amount, and that period must end no more than 31 days before you apply. You need unpaid fees plus £1,529 a month in London or £1,171 elsewhere for up to 9 months (rising to £1,570 and £1,203 for applications from 30 November 2026).
Can an education loan be shown as proof of funds?
Yes, in all of these countries a sanction letter from a bank or NBFC is accepted, provided it meets each country's rules (for the UK, from a regulated lender and in your name). A loan also avoids tax collected at source when you send fees abroad.
Is TCS charged on fees sent abroad for education?
Not if the money comes from an education loan from a bank or NBFC (nil since 1 April 2025). Self-funded education payments attract TCS on the amount above ₹10 lakh in a financial year, cut from 5% to 2% from 1 April 2026, and you can claim it back as a credit in your tax return.
Can my relatives sponsor my studies?
Canada, the USA, Australia and New Zealand accept sponsors such as parents or close relatives if their income and the source of funds are shown. The UK accepts only your own money or a parent's or legal guardian's, an official financial sponsor, or an education loan in your own name. Germany usually needs a blocked account or a formal obligation letter.
Do property or gold count as proof of funds?
Generally no: officers want money you can use now. Property, gold and provident fund balances can support where the money came from, but you usually need liquid savings, a fixed deposit or a loan for the amount itself.
Sources
Figures on this page were checked against these sources on 3 November 2026. Rules change: confirm on the official site before you apply.
- CIC News: Canada study permit funds rise to C$23,448 from 1 September 2026
- OTS Solicitors: UK student maintenance funds from 30 November 2026
- Garth Coates: UK Student visa refusals and the 28-day rule
- Flywire: TCS on foreign education payments from 1 April 2026
- Business Standard: no TCS on foreign education loans
- One Planet Migration Law: student visa financial capacity in 2026 (A$29,710)
- Expatrio: blocked account amount (€11,904, €992 a month)